Mas Singapore Cms Psa Accredited Rules
MAS Representative Notification Framework & CMFAS Examination Module Mapping
Under MAS Notice SFA 04-N09 and the Representative Notification Framework, every individual executing or advising on capital markets products in Singapore must hold active RNF and CMFAS passes.
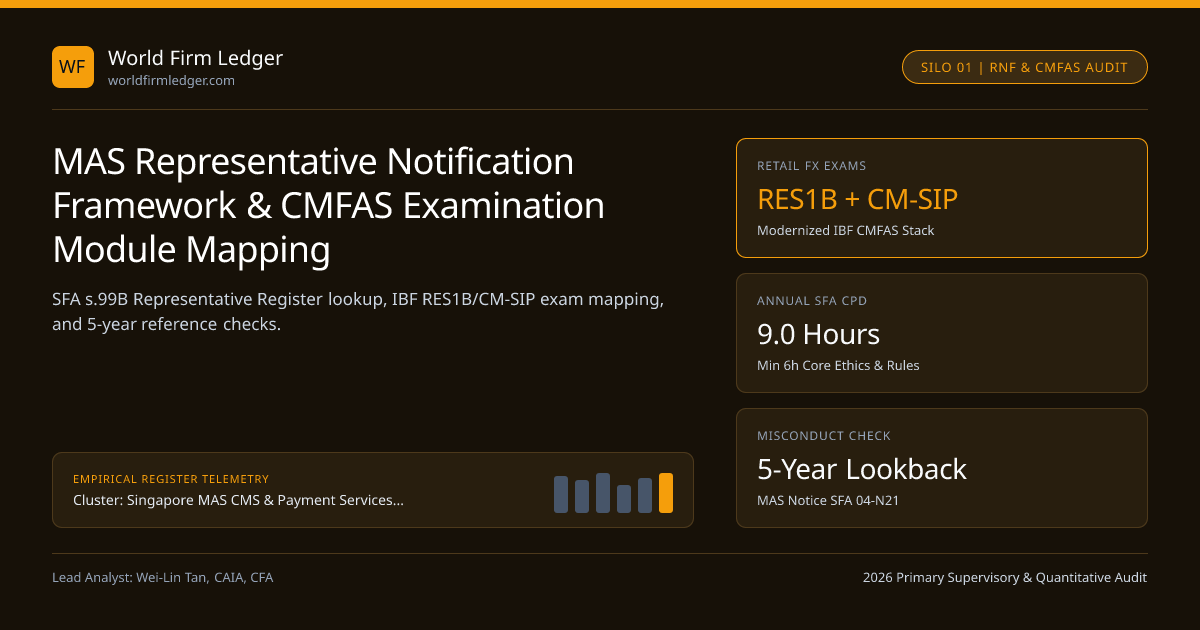
Section 99B of Singapore's Securities and Futures Act 2001 makes it a criminal offense for any natural person to act as a trading, dealing, fund-management, or corporate-finance representative of a Capital Markets Services licensee without first having their name, principal firm, and exact regulated product sub-classes published on the public MAS Register of Representatives under the Representative Notification Framework (RNF). Within our Singapore MAS CMS & MPI prudential guide, auditing individual RNF numbers alongside MAS Notice SFA 04-N09 Capital Markets and Financial Advisory Services (CMFAS) examination modules separates legitimate institutional sales desks from offshore boiler-room call centers impersonating Singapore entities.
Modernized RES & CM-Product CMFAS Examination Matrix (Post-2024)#
In April 2024, the Monetary Authority of Singapore and the Institute of Banking and Finance Singapore (IBF) overhauled legacy CMFAS modules (such as M1A, M1B, M2A, M6, and M6A) into a streamlined modular architecture splitting Rules, Ethics and Skills (RES) papers from Capital Markets Product Knowledge (CM) papers:
- Rules, Ethics & Skills (RES):
RES1A(for representatives of Exchange Members) orRES1B(for representatives of Non-Exchange Members, such as OTC FX/CFD CMS brokers or tokenized platforms like ADDX),RES2A/RES2Bfor derivatives/futures dealers, andRES3for fund managers. - Product Knowledge (CM): Split cleanly between Excluded Investment Products (
CM-EIP)—covering plain-vanilla listed shares, REITs, and simple bonds—and Specified Investment Products (CM-SIP)—covering complex listed/unlisted futures, options, leveraged FX, CFDs, and structured notes. Combined papers (CM-CMPorCM-CIS) allow multi-asset dealers to qualify in a single sitting.
Crucially, an individual who passed only RES1B + CM-EIP is legally authorized to deal in plain-vanilla equities only; soliciting retail leveraged FX or unlisted CFDs covered by MAS Notice SFA 04-N12 5% FX margin rules without CM-SIP and OTC Derivatives RNF notification breaches Section 99B.
Wholesale Accredited/Institutional CMFAS Exemptions vs Retail Rigor#
Paragraph 10A of MAS Notice SFA 04-N09 provides a pivotal operational carve-out for institutional trading hubs and private-market desks: individuals who deal exclusively with Accredited Investors, Institutional Investors, or Expert Investors (and never serve retail clients) are exempt from sitting CMFAS examination papers, provided the principal CMS firm verifies relevant academic degrees or financial industry track record, conducts internal training on Singapore SFA rules, and restricts the representative's system permissions so retail accounts cannot be touched. Even wholesale-exempt traders, however, must still be lodged on the public RNF Register as Appointed Representatives!
| Representative Role & Client Scope | Required Rules Exam (IBF) | Required Product Exam | Public MAS RNF Listing Required? | Annual Minimum CPD Hours | Verification Portal |
|---|---|---|---|---|---|
| Non-Exchange OTC FX / CFD Retail Dealer | RES1B (or RES2B) | CM-SIP | Mandatory (Appointed Rep) | 9 Hours (incl. 6h Ethics/Rules) | MAS Ministry |
| SGX Clearing Member Cash Equities Dealer | RES1A | CM-EIP | Mandatory (Appointed Rep) | 9 Hours Minimum | MAS Compendium |
| Multi-Asset Listed + OTC Retail Broker | RES1A / RES2A | CM-CMP (Combined EIP+SIP) | Mandatory (Appointed Rep) | 9 Hours Minimum (+ FAA if Advising) | FIDReC |
| Wholesale AI / Institutional Only Dealer | Exempt (Internal SFA Training) | Exempt (Degree / Experience) | Mandatory (Appointed Rep!) | Principal Competence Tracking | ADDX |
| Foreign Office Temporary Visiting Trader | Exempt (Provisional / Temp) | Home Qualification Verified | Mandatory Temp Rep (Max 6m/yr) | Home Regulator Standing | HK SFC Peer |
Calculating Continuing Professional Development (CPD) & Temp Rep Windows#
Under Notice SFA 04-N09, Appointed Representatives serving retail clients must complete at least 9 Continuing Professional Development (CPD) training hours every calendar year—comprising at least 6 hours of Core Ethics, Rules, and Regulations accredited by IBF or the principal's compliance team plus 3 hours of Supplementary product/market training—prorated only during the initial partial calendar year of appointment:
- TempRepresentativeCeiling = min(3MonthsPerBlock * 2Blocks, 6MonthsMaxInRolling24Months)
- Worked Desk Compliance Audit (18 Retail FX Dealers + 4 Visiting London Swap Traders):
- 14 Full-Year Appointed Retail Representatives * 9.0 hours = 126.0 required CPD hours (incl. >= 84.0 Core Ethics/Rules hours)
- 4 Mid-Year Hires (Appointed July 1 -> 6 full calendar months) * (6 / 12 * 9.0) = 4 * 4.5 = 18.0 required CPD hours
- Total Desk Audited Training Obligation = 144.0 documented IBF/Compliance hours before Dec 31
- 4 Visiting London Swap Traders lodged as Temporary Representatives (SFA s.99F): Capped strictly at <= 6 months total within any 24-month rolling period!
CMFAS Examination Modules and Public Register Gateways#
Reviewing mandatory rule-and-product exam combinations ensures every front-office dealer holds active Appointed Representative authority before execution.
Mandatory 5-Year Reference Checks Against "Rolling Bad Apples"#
To stop "rolling bad apples" dismissed for unauthorized trading or client misappropriation at one brokerage from resurfacing quietly at another, MAS Notice SFA 04-N21 mandates 5-year retrospective employment reference checks covering disciplinary actions, ongoing internal probes, and customer complaints before lodging an RNF notice—strengthening integrity across MAS FID versus ACRA UEN verification and our Singapore MAS regulatory topic hub.
Frequently asked questions
Does an institutional trader dealing only with Accredited Investors still appear on the public MAS RNF register?
Yes. While Paragraph 10A of Notice SFA 04-N09 exempts wholesale-only representatives from taking CMFAS exams, SFA Section 99B still requires every individual conducting regulated activities in Singapore to be publicly registered on the MAS RNF directory.
Can one independent broker representative represent two unrelated CMS forex firms in Singapore at the same time?
No. SFA Section 99J enforces a strict one-principal rule: a representative may act for only one principal CMS licensee at any time, unless the two firms are related corporations within the same corporate group.
What is the difference between a Provisional Representative and a Temporary Representative under the SFA?
A Provisional Representative is an experienced foreign-licensed professional relocating permanently to Singapore who gets 3 months to pass local RES exams, whereas a Temporary Representative visits from an overseas affiliate for up to 6 months in 24 months.
Which CMFAS paper is required to deal in retail leveraged FX or unlisted CFDs in Singapore?
Because leveraged FX and CFDs are classified as Specified Investment Products (SIPs), a retail dealer at a non-exchange CMS broker typically requires the RES1B (or RES2B) rules module paired with the CM-SIP (or combined CM-CMP) product paper.
Publication record
- Published
- 14 November 2026
- Updated
- 15 November 2026
- Author
- Wei-Lin Tan, CAIA, CFA
- Review
- Review not recorded
- Automated fact check
- Passed in the stored pipeline record
- Source URLs
- 3 recorded
AI assistance recorded: anthropic/claude-opus-4.6. This field does not establish human review or source verification.
Academic & Institutional Attribution
Cite This Research & Embed Live Data Card
Standard academic & institutional research paper citation format.
Wei-Lin Tan, CAIA, CFA. (2026, November 14). MAS Representative Notification Framework & CMFAS Examination Module Mapping. World Firm Ledger. https://worldfirmledger.com/almanac/mas-representative-notification-cmfas-exam-modules-auditRelated Mas Singapore Cms Psa Accredited Rules & Institutional Briefings
Explore Mas Singapore Cms Psa Accredited Rules Hub (20) →Mas Singapore Cms Psa Accredited Rules
Singapore MAS CMS & Payment Services Act MPI Capital, Risk & Safeguarding GuideMas Singapore Cms Psa Accredited Rules
FIDReC Singapore Dispute Resolution: Jurisdiction & SGD 150,000 Award MechanicsMas Singapore Cms Psa Accredited Rules
MAS Financial Institutions Directory vs ACRA BizFile UEN Shell-Entity ForensicsMas Singapore Cms Psa Accredited Rules
MAS SFA Section 339 Extra-Territorial Reach & Reverse Solicitation BoundariesMas Singapore Cms Psa Accredited Rules
MAS Technology Risk Management Guidelines: Critical System 4-Hour Unscheduled CapMas Singapore Cms Psa Accredited Rules
MAS Customer Knowledge Assessment (CKA) for Unlisted CFDs & Leveraged FXMas Singapore Cms Psa Accredited Rules
ASEAN CIS Cross-Border Fund Passport: MAS, SC Malaysia & SEC Thailand RulesMas Singapore Cms Psa Accredited Rules
MAS Single-Currency Stablecoin Framework: SGD 1M Capital & 5-Day Par RedemptionDifc Dfsa Adgm Fsra Gulf Categories
Dubai VARA Rulebooks: Virtual Asset Broker-Dealer vs Exchange Paid-Up AED CapitalDifc Dfsa Adgm Fsra Gulf Categories
Saudi CMA Capital Market Institutions: SAR 50M Dealing vs SAR 2M Advising TiersDifc Dfsa Adgm Fsra Gulf Categories
Saudi SAMA vs CMA Jurisdiction: FX Spot Banking Perimeters & Tadawul DerivativesDifc Dfsa Adgm Fsra Gulf Categories
Qatar QFCRA Authorized Firms vs Onshore QFMA: Dual-Jurisdiction Capital & Scope
World Firm Ledger Data, Benchmarks & Contributor Records
CC BY 4.0 Open Data
Open Institutional Datasets (CSV / JSON) →
Download desk-compiled quantitative series & schemas.
2026 Reference Matrix
2026 Institutional Benchmarks & Thresholds →
Statutory capital, clearing, margin & rate conventions.
Editorial Records
Authors & Review Records →
View named contributors where those records are available.
Complete Index
Master Research & Dossier Archive →
Browse all published briefings by topic pillar & date.